Most sellers ask one question about cost: how much? The better question is when. The total cost to sell a home in Northern Virginia arrives in two waves: cash you pay before closing, and deductions taken out of your proceeds at settlement.
Mix those up and you can run short of cash in the middle of a sale, even with plenty of equity in the house. Equity pays the closing-day bills. The painter three weeks before you list gets paid from savings.
This guide is about timing. For the overall size of the bill, including typical commissions and closing-cost ranges, start with our breakdown of how much it costs to sell a home in Northern Virginia. For how the listing fee itself can change your number, see our guide to a low commission realtor in Northern Virginia. I have spent 24+ years in Northern Virginia real estate and closed more than 2,000 transactions, and the cash-timing questions below come up on nearly every sale.
Total cost to sell a home in Northern Virginia: what needs paying upfront?
Budget your upfront cash separately from your eventual proceeds. Repairs, staging, deposits, and moving costs usually come out of your pocket before settlement, and your sale money is not available yet.
These are the upfront costs of selling a house that sellers most often underestimate. Each one runs on the vendor’s timeline:
- Repairs and prep. Painters, handymen, and contractors typically bill when the work is done, which is before the home goes on the market.
- Staging. NAR’s 2025 Profile of Home Staging found a national median of $1,500 when sellers used a staging service. That is a national median. Northern Virginia quotes can differ.
- Deposits. Movers, storage units, and some vendors may ask for a deposit to hold a date.
- Moving. Many sellers move out before settlement, which means paying for the move with savings.
- Any fee your listing agreement collects upfront. Some agreements include a retainer or admin fee paid at signing.
Source for staging figure: NAR, 2025 Profile of Home Staging (May 6, 2025).
Before you sign with any vendor, ask two questions: when is payment due, and can it wait until settlement? Get the answer in writing. A contractor who will bill at closing through the settlement agent changes your cash plan completely.
The mistake I see most is treating the total cost to sell a home in Northern Virginia as one number. Split it into two columns: cash out of your account before closing, and money deducted at closing. The first column decides how much savings you need. The second decides your net check.
The seller expenses before closing also depend on your prep plan. Our step-by-step home selling checklist for Northern Virginia lays out the prep sequence so you can see which bills land in which week.
How much cash should you set aside before listing?
Build a dated list. Write down every vendor, the amount, and the date each bill is due. Add up everything due before your target settlement date. That total is your upfront cash need.
Then add a buffer for the unexpected, such as a repair a buyer’s inspection turns up that you choose to fix yourself. The delayed-closing math later in this guide shows one way to size it. If the total is more than you want to spend from savings, move items to the closing column where you can, using the options in the next section.
What comes out of the closing payout?
At settlement, the settlement agent deducts your listing fee, transfer taxes, any credits you agreed to give the buyer, and your mortgage payoff. List each one once, and mark what you already paid so you do not count it twice.
Here is a hypothetical $1,000,000 Fairfax County sale to show the timing. The transfer charges use Fairfax Circuit Court rates effective July 1, 2026. The other figures are assumptions for illustration.
| Expense | Amount | When it is due | Already paid | Deducted at closing |
|---|---|---|---|---|
| Staging (assumed) | $1,500 | Before listing | $1,500 | $0 |
| Listing fee, $500 + 1% (example) | $10,500 | $500 at signing, 1% at settlement | $500 | $10,000 |
| Virginia grantor tax ($0.10 per $100) | $1,000 | Settlement | $0 | $1,000 |
| Regional congestion relief fee ($0.10 per $100) | $1,000 | Settlement | $0 | $1,000 |
| Regional WMATA capital fee ($0.10 per $100) | $1,000 | Settlement | $0 | $1,000 |
| Repair credit to buyer (assumed) | $5,000 | Settlement | $0 | $5,000 |
| Mortgage payoff (assumed) | Per payoff statement | Settlement | $0 | Full payoff amount |
Illustration only. Hypothetical Fairfax County sale; staging, listing fee, repair credit, and payoff are assumptions, and other settlement charges are not shown. Transfer charges: Fairfax Circuit Court land records fee schedule, effective July 1, 2026.
Read the listing fee row closely. The $10,500 fee is one cost, paid in two moments. If you add the full $10,500 to the closing column after already paying $500, you overstate your costs. That is the double-counting trap.
The repair credit row shows a timing lever. If a buyer’s inspection turns up a $5,000 problem, you can fix it yourself before settlement, or agree to a credit. Fixing it means paying a contractor from savings. A credit means the same $5,000 comes out of your proceeds at closing. The cost can be similar, but the cash timing is very different. Talk through the choice with your agent before you respond to the buyer.
The three transfer charges total $3,000 on a $1,000,000 sale, or $0.30 per $100. Fairfax’s schedule lists all three for deeds, and a Northern Virginia seller customarily pays them. Your settlement agent will confirm the exact figures for your jurisdiction.
Why is the mortgage payoff its own line?
Because it is not the same as your balance. The CFPB explains that your payoff amount includes interest through your payoff date, plus any fees owed, so it differs from your current balance (CFPB, 2026). Your servicer generally has seven business days to answer a payoff request, so order it early (CFPB).
This is the heart of the total cost to sell a home in Northern Virginia: the principal you repay is your own debt going away. It lowers your check, and it is still your equity at work, so leave it out of your selling costs. The accrued interest is a real cost. After closing, keep the settlement statement. Our guide on why you should keep your ALTA explains what to look for.
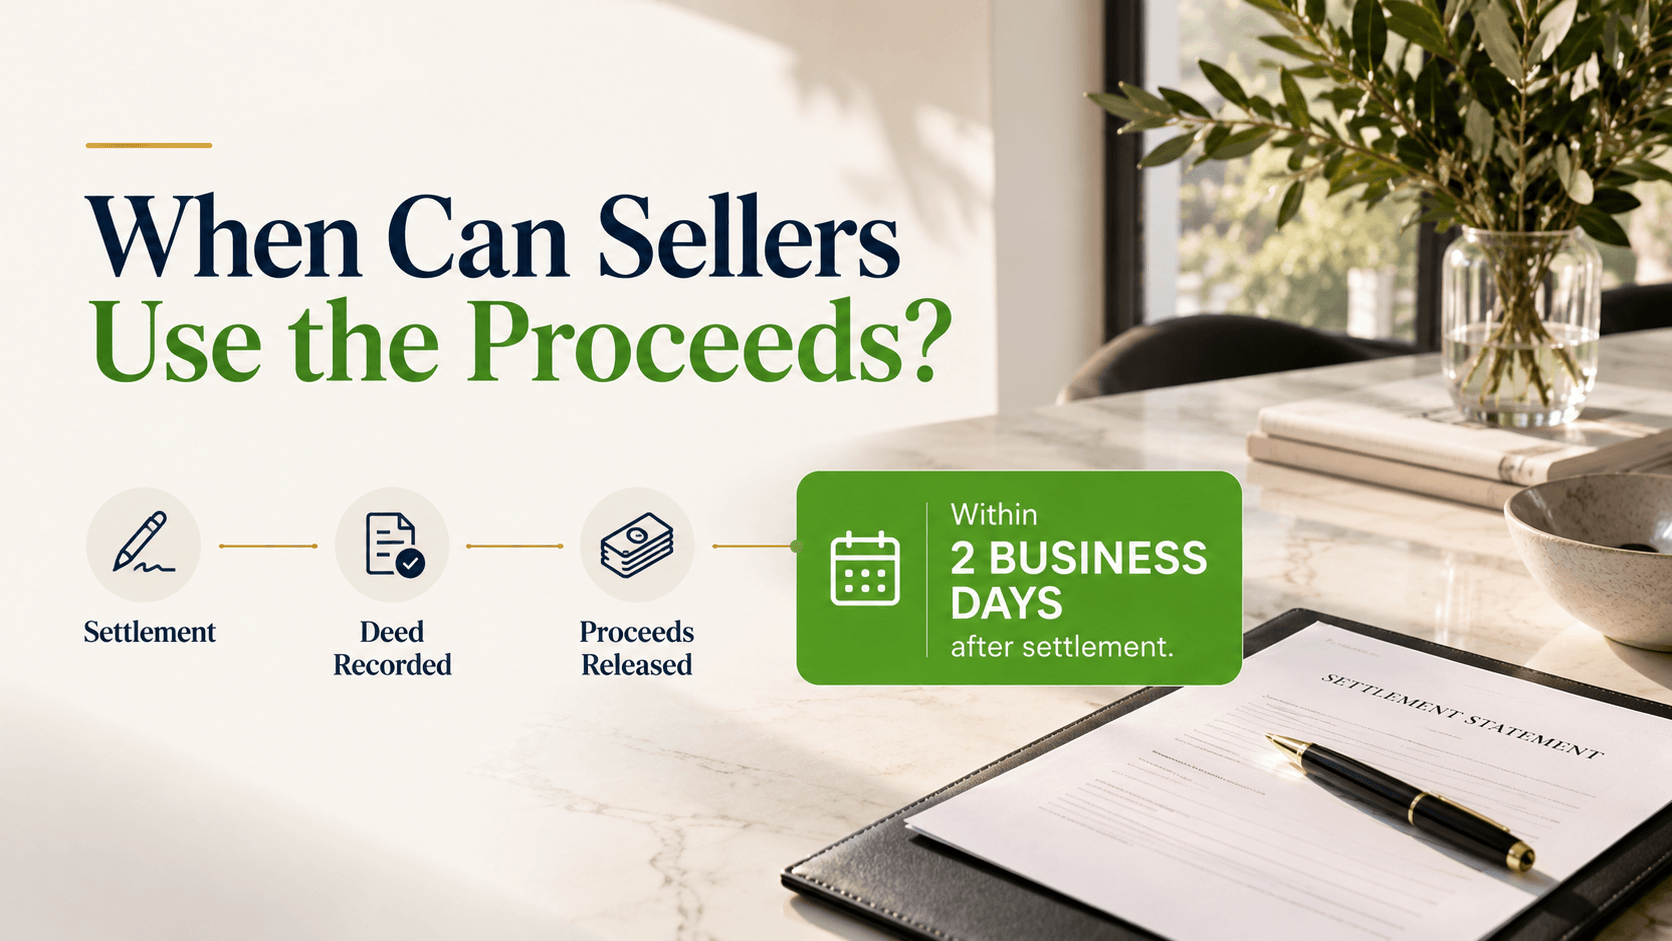
When can sellers use the proceeds?
Soon after settlement, once the deed is recorded. Virginia law requires the settlement agent to disburse settlement proceeds within two business days of settlement.
The same statute generally bars disbursement before the deed and other required documents are recorded, with narrow exceptions (Virginia Code § 55.1-903).
In practice, that means a short gap between signing and money in your account. Plan around it.
Before settlement, ask your settlement agent four things:
- When do you expect the deed to be recorded?
- What day will my proceeds be released?
- Will I receive a wire or a check?
- What do you need from me, such as wiring details, to avoid a delay?
If you are buying your next home the same week, do not count on today’s sale to fund today’s purchase. Talk to both settlement agents early. Ask when your funds will be released and whether the timing works for your next closing.
The same goes for moving day. If movers want their final payment on the day you close, that money will likely come from savings. Your proceeds follow a day or two later.
How does a delayed closing change cash needs?
A delay means you keep paying to own the home. Fund those extra carrying costs from cash, and ask for an updated payoff statement for the new settlement date.
Here is a hypothetical Great Falls seller whose settlement slips by 30 days. Say their carrying costs, meaning mortgage interest, taxes, insurance, utilities, and upkeep, work out to $150 a day.
| Item | Amount |
|---|---|
| Daily carrying cost (assumed) | $150 |
| Days of delay | 30 |
| Cash buffer to plan for | $4,500 |
Illustration only. Hypothetical Great Falls seller with an assumed daily cost. This is not a market estimate or a documented transaction.
Split that daily cost in two. The principal part of any mortgage payment you make stays yours. It lowers your payoff, so you get it back in proceeds. The interest, taxes, insurance, and utilities are true costs. Interest keeps running until your loan is paid off, which is why your payoff figure must match the new date.
So the total cost to sell a home in Northern Virginia can rise even when nothing else changes. A delay adds carrying costs and shifts every payoff figure. Build a buffer before listing, sized to at least one month of ownership costs.
Your next step
Every cash plan starts with one number: what your home is likely to sell for. That tells you how big your closing-day deductions will be, and how much savings to hold back for the upfront column.
Get your Free Home Valuation Report. Then build your two-column plan: cash before closing, and deductions at closing. No pressure and no obligation.

About Michael Gorman
Michael Gorman is the founder and Principal Broker of RealtyPeople, a full-service brokerage serving Northern Virginia. He holds a Harvard MBA, has 24+ years in the business, 2,000+ transactions closed, and more than $2 billion in volume. He is an NVAR Diamond Top Producer for 10+ consecutive years and a former Senior Vice President at Long & Foster. Mike runs every file personally, start to finish.
View profile →Compliance and disclosures: Savings figures use “can save” examples, not guarantees. They assume a 2.5% seller-paid listing commission under a traditional model, separate from any buyer-agent compensation. Buyer cash back assumes the seller offers a buyer-agent commission of at least 1% and is subject to loan-program limits. Commission and fee data are from 2026 industry sources; price context is from NVAR. No outcome on sale price, time on market, or savings is guaranteed. This article is general information, not legal, tax, or financial advice.
RealtyPeople is a licensed real estate brokerage in Virginia. Michael Gorman is a licensed Principal Broker in Virginia. Equal Housing Opportunity.
